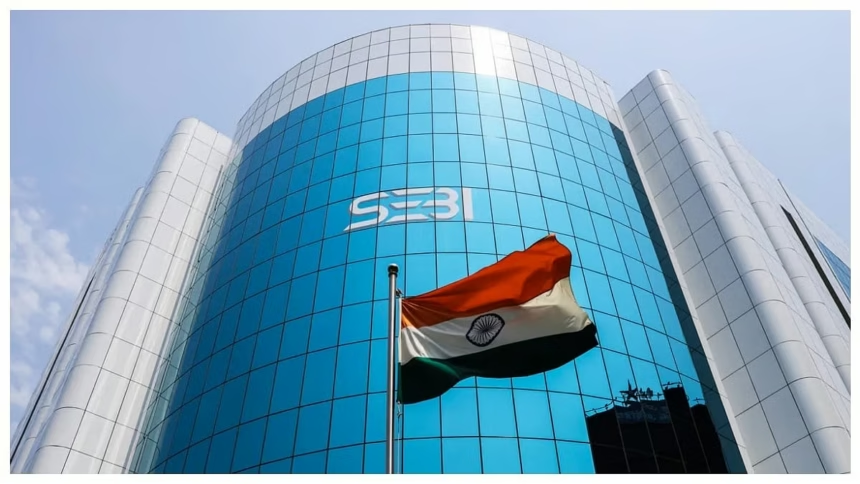
The Sebi closing auction session framework has been revised to change trading timings and the methodology for determining settlement prices of stock and index derivatives contracts.
Under the revised rules, the 10-minute Closing Auction Session (CAS) will run from 3:30 pm to 3:40 pm on all trading days. Trading in index and stock derivatives will continue until 3:45 pm, subject to certain exceptions for expiring index derivatives contracts.
The Securities and Exchange Board of India (Sebi) said the changes aim to improve transparency, strengthen price discovery and ensure a more orderly market close.
Most modifications will take effect from December 7, 2026. The provisions governing the transition of unexecuted limit and iceberg orders from continuous trading to the closing auction session will come into force on February 8, 2027.
Sebi revises closing auction session timings
Under the revised schedule, the closing auction session will begin at 3:30 pm with reference price calculation and the transition of orders from the continuous trading session.
Order entry for both limit and market orders will be allowed from 3:31 pm to 3:36 pm. After this window, only limit orders can be placed. The session will close randomly between 3:38 pm and 3:40 pm.
The post-close session in the equity cash segment will run from 3:50 pm to 4 pm. Trades during this period will be executed at the closing prices of securities.
For determining the reference price used in CAS, Sebi will use the volume weighted average price (VWAP) of trades executed during the final 15 minutes of continuous trading.
If no trade takes place during this period, the security’s last traded price of the day will be used. If there are no trades throughout the day, the previous trading day’s closing price will serve as the reference, adjusted for corporate actions wherever applicable.
VWAP methodology for derivatives settlement
A key change under the Sebi closing auction session framework concerns the settlement prices of expiring derivatives contracts.
For index derivatives, the expiry-day settlement price will be based on the underlying index value calculated using the VWAP of constituent securities during the final 30 minutes of continuous trading in the equity cash segment.
For stock derivatives, settlement prices will be determined using the VWAP of the underlying stock during the final 30 minutes of continuous trading across all stock exchanges.
Stock exchanges will calculate and disseminate indicative underlying index values and indicative VWAPs of securities in real time during the relevant period to improve transparency.
Sebi has also specified that stock futures’ price bands between 3:30 pm and 3:45 pm will align with those applicable during the closing auction session. The existing framework for dynamically adjusting price bands will not apply to stock futures during this period.
Changes follow review of existing framework
Sebi introduced the CAS framework in the equity cash segment from August 3 to determine securities’ closing prices. Under the existing framework, the closing price determined through CAS also serves as the basis for calculating settlement prices of derivatives contracts on expiry.
Following concerns over this methodology, Sebi proposed changes in September and issued a consultation paper seeking public comments.
The revised framework follows a review of the existing rules, consideration of public feedback, recommendations from Sebi’s Secondary Market Advisory Committee and discussions with stock exchanges.